You’re funding retirement, but taxes feel unknowable
The decision usually shows up at an ordinary moment: a raise kicks in, a bonus lands, or you finally automate monthly transfers. Then the form asks the question that doesn’t feel answerable—Roth or pre-tax—and the stakes suddenly feel larger than the dollar amount. Tax rates might be higher later, but your income might be lower. Congress could change rules, but your own job could change first. Meanwhile, the deadline is real, and the cash has to go somewhere.
What makes it tricky is that the “right” choice depends on details you can’t spreadsheet cleanly: today’s marginal bracket, whether you’ll max a 401(k) match first, and how much flexibility you’ll need before age 59½. The friction isn’t confusion—it’s committing to a tax bet without knowing which year ends up being expensive.
The common Roth IRA mistake: paying peak taxes
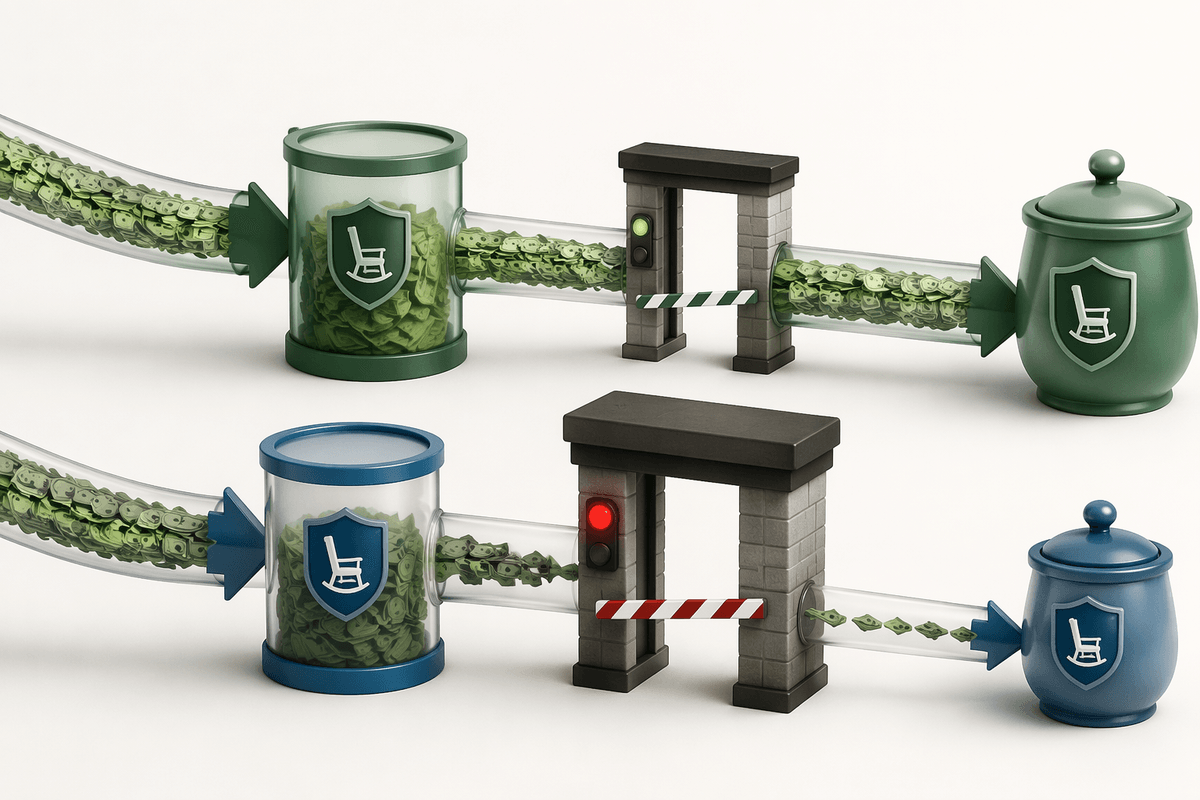
After that first decision point, the most common pattern is surprisingly consistent: people default to Roth the year their paycheck is at its best. A promotion hits, RSUs vest, a spouse goes back to work, and the “just pay taxes now” logic feels clean. The constraint is immediate, though—Roth dollars are funded with after-tax money, so the same monthly contribution requires more take-home pay. If cash flow is tight, that often means contributing less than you otherwise could, or skipping pre-tax options that would have lowered today’s bill.
The mistake isn’t choosing Roth at all; it’s choosing Roth at your peak marginal rate without checking what would happen if this is a high-income stretch. In a top bracket year, every Roth dollar is effectively bought at that bracket, even if retirement withdrawals later would mostly fall into lower brackets. The trade-off becomes concrete when you realize the tax “certainty” you purchased was also your most expensive year to buy it.
What it costs later: less saved, fewer options
Once you pay peak-rate taxes up front, the long-term cost often shows up as a quiet contribution ceiling. The IRA limit doesn’t rise just because you chose after-tax dollars, so a Roth choice in a high-bracket year can translate into less total retirement money working for you. If the same household could have maxed a pre-tax 401(k) and then added an IRA, the Roth-first instinct sometimes flips the order—because the paycheck has to absorb the tax friction immediately, not decades later.
The second cost is optionality. Pre-tax space can create “room” later for controlled income—filling lower brackets in early retirement, smoothing years between work and Social Security, or managing Medicare IRMAA exposure. When too much of the plan is funded with Roth bought at expensive rates, the portfolio may be tax-free but less adjustable. The constraint isn’t just future tax rates; it’s fewer levers when the timeline or income path changes.
When a Roth IRA is most defensible: low-tax years
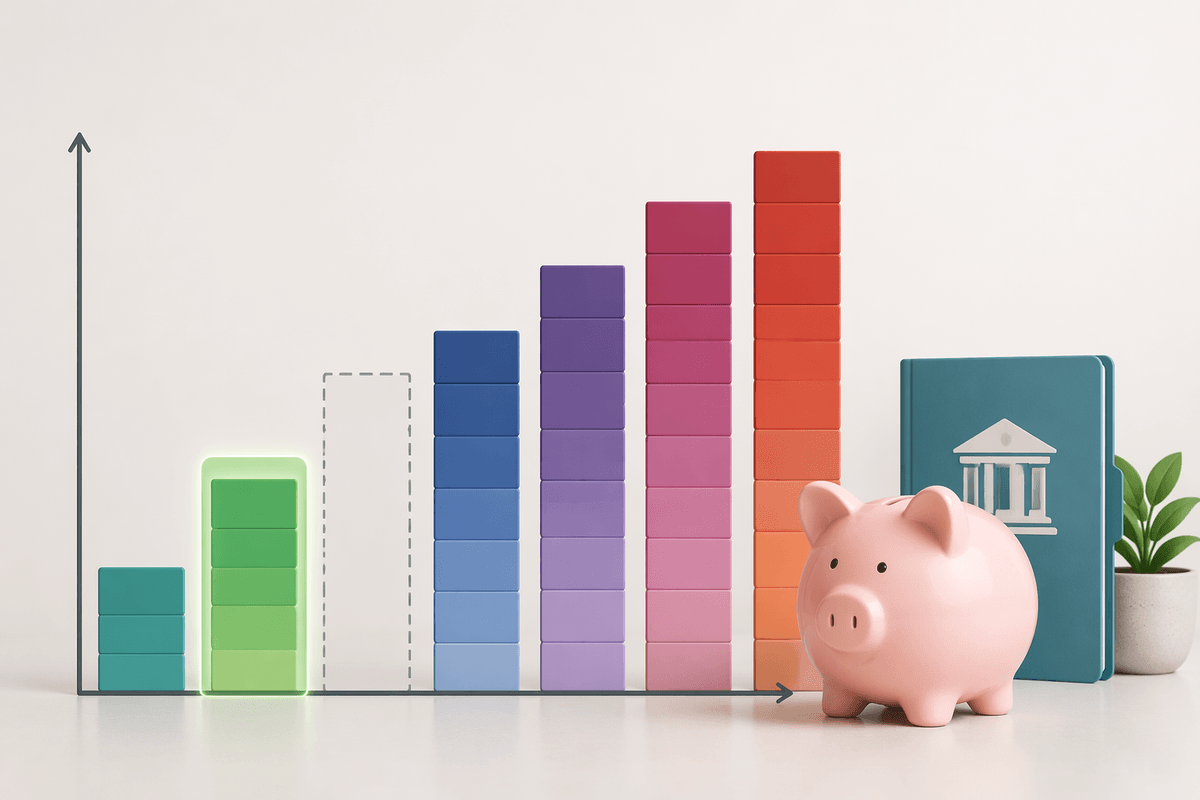
Still, there are years when Roth stops looking like an overpriced “tax prepayment” and starts looking like a clean purchase. The tell is usually on your tax return, not in your preferences: income is temporarily down, deductions are temporarily up, or you’re early enough in a career arc that the marginal bracket is meaningfully lower than what your household normally lives in. In those years, the cash-flow hit of after-tax saving is real, but you’re buying tax-free growth at a discount relative to your likely earning years.
The most defensible Roth contributions tend to cluster around transitions with constraints: a job change with a gap, a sabbatical, a move to part-time, parental leave, or the first years after a spouse stops working. In practice, people notice it when the last dollars of income are sitting in a lower bracket than usual and there’s room before the next bracket kicks in. That’s when paying the tax now can be rational—because the “now” tax is unusually cheap, not because the future is certain.
When future withdrawals will be ‘expensive’ by design
There’s another bucket of years where Roth starts to look less like a “low-tax-year” play and more like insurance against a plan that is set up to generate taxable income later. The pattern is usually visible before retirement: a meaningful pension, large pre-tax 401(k) balances that will eventually face required minimum distributions, or a household that expects Social Security to stack on top of those withdrawals rather than replace wages. In that setup, retirement isn’t a low-income phase—it’s a scheduled income floor.
The constraint is that the tax system prices the last dollars of income, not the first. When RMDs arrive on a large pre-tax base, they can push ordinary income into higher brackets, trigger Medicare IRMAA surcharges, or compress brackets after the first spouse dies (the “widow(er) penalty” turns the same income into a higher marginal rate). In those cases, paying some tax earlier via Roth isn’t about predicting Congress—it’s about acknowledging your own future cash-flow design may already be expensive.
Flexibility matters: access, timing, and no RMDs
Even when the tax math is close, the tie often breaks on logistics. A Roth IRA has a different feel in real life because contributions (not earnings) can usually be pulled back out without tax or penalty. That doesn’t make it a checking account—selling investments still has timing risk, and pulling money can permanently shrink retirement space—but it can matter for uneven cash needs: a house down payment that moves up a year, a layoff that lasts longer than expected, or a bridge to age 59½ when the plan changes.
Then there’s the calendar problem in later years. If you expect lumpy income—consulting, a one-time business sale, big capital gains—Roth dollars give you something to spend without stacking more ordinary income on top. And unlike pre-tax retirement accounts, Roth IRAs don’t force required minimum distributions during the owner’s lifetime, which can keep taxable income lower on purpose. The constraint is subtle: flexibility is valuable, but only after you’ve paid for it with today’s tax bill.
A final filter: Roth IRA after checking alternatives
By the time you reach for the Roth IRA, it helps to treat it like the last slot, not the first. The quick check is whether you’ve already taken any “free” or structurally better space: a full 401(k) match, a pre-tax 401(k) contribution that clearly drops your marginal bracket, or an HSA if you can actually leave it invested. Those choices change today’s tax bill immediately, and the constraint is simple—there’s only so much cash flow to fund all of them at once.
If those boxes are checked, Roth becomes cleaner: either you’re in a deliberately low bracket year, or you’re building a pool of tax-free spending for years when taxable income will be crowded. If neither is true, the final filter is blunt: confirm your current marginal rate, confirm eligibility, and decide whether the flexibility is worth paying that rate this year.